The Beaver Ledger: Can Private Capital Underwrite Devon's River Restoration?
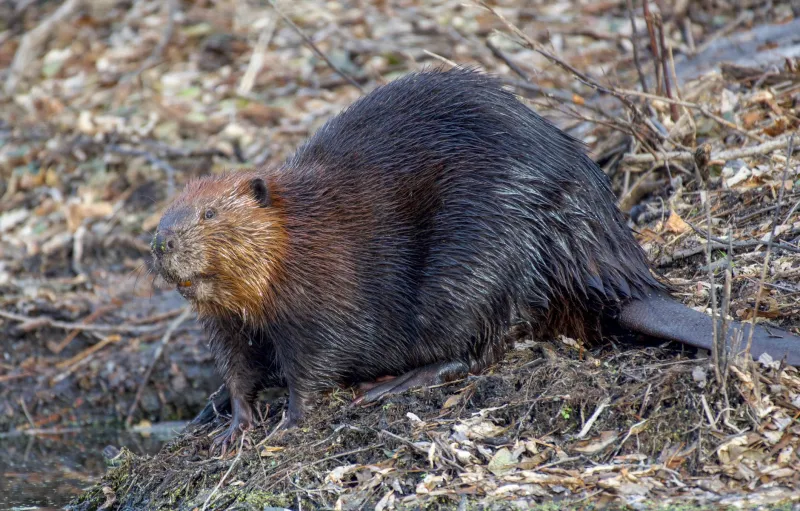
On the River Otter, the beavers are doing what beavers do: building dams, digging canals, slowing water and creating wetlands. For conservationists, the animals are a form of low-cost catchment engineering. For financiers, they are something more awkward — a biological process that is difficult to measure, predict and insure. As Devon's beaver trial expands, the question is no longer simply whether the animals belong in the landscape. It is who pays for their work, and on what terms.
The traditional answer has been grants, charitable funding and public money. That model has limits. Habitat restoration is expensive to monitor and slow to deliver. Flood risk is rising. Biodiversity net gain (BNG) has created a new market in habitat units, and some landowners and investors now see beaver-engineered wetlands as a potential source of credits. Flood-risk bonds, meanwhile, are being discussed as a way to tie repayment to reduced downstream flood damage. Both ideas are plausible. Neither is simple.
From grants to ledgers
Biodiversity net gain requires developers to deliver a measurable improvement in habitat, usually through off-site units purchased from a land manager. In principle, a beaver wetland could generate such units: open water, wetland scrub, wet woodland and braided channels can all score well against habitat metrics. In practice, beaver activity is dynamic. A dam may be abandoned, a pond may silt up, a channel may move. The habitat that exists at the point of sale may not be the habitat that exists ten or thirty years later.
That matters because BNG credits are meant to be durable. The legal agreements behind them typically run for decades, with monitoring and management obligations attached. A landowner who sells credits for a beaver wetland is not simply selling a pond. They are selling a future state that depends on animals, hydrology, weather and neighbouring land use. The contract may be clear. The ecology is not.
Flood-risk bonds present a different challenge. The idea is to raise capital for restoration and repay investors from savings in flood damage or from payments by beneficiaries such as downstream property owners, insurers or public bodies. In theory, beaver dams and wetlands can attenuate peak flows and reduce flood peaks. In practice, the evidence is site-specific. A beaver wetland that stores water in a small catchment may have little effect on a large river. The benefits may be real but difficult to isolate from other interventions.
Who really pays?
Interviews with landowners, the Environment Agency and green investors suggest a shared enthusiasm and a shared caution. Landowners see an opportunity to diversify income and fund long-term management. The Environment Agency is interested in natural flood management but wary of promises that outrun the evidence. Investors want measurable outcomes, clear governance and an exit route. None of these positions is unreasonable. Together, they expose the central tension: private capital needs certainty, while beaver-led restoration is inherently uncertain.
There is also a question of who carries liability. If a beaver dam contributes to flooding on a neighbouring field, who is responsible? If a wetland fails to deliver the biodiversity units promised, who makes up the shortfall? If a flood-risk bond underperforms because the animals build in the wrong place, who absorbs the loss? These are not hypothetical concerns. They are the kind of questions that determine whether a financial structure is bankable or merely imaginative.
The metrics problem
Beaver banking, as the more speculative version of this agenda is sometimes called, risks prioritising sites that can produce credits over sites that are ecologically important. A catchment with good access, willing landowners and straightforward hydrology may attract finance, while a more valuable but complex site remains unfunded. That is a familiar pattern in payments for ecosystem services. Markets tend to reward what can be measured and sold, not necessarily what matters most.
There is a further risk of double counting. A beaver wetland may deliver biodiversity benefits, flood attenuation, water quality improvements and carbon storage. Each of these can be claimed by a different funder or market. Without careful accounting, the same pond can be sold several times over. The governance of these schemes therefore matters as much as the ecology. Independent verification, transparent baselines and clear rules on stacking and additionality are essential.
None of this means private finance should be rejected. Public money alone is unlikely to restore the scale of wetland and river habitat that climate adaptation and nature recovery require. But private capital is not a neutral substitute for public funding. It brings its own priorities, timescales and expectations. If beaver restoration is shaped around the needs of investors, it may become narrower and more fragile than the catchment-wide approach that ecologists recommend.
Can rodents underwrite resilience?
The more modest conclusion is that beavers can contribute to catchment resilience, but they cannot underwrite it alone. They are one part of a portfolio that should include leaky dams, floodplain reconnection, soil management, tree planting and conventional engineering where needed. Private finance can support that portfolio, but it should not be asked to carry risks it cannot price.
For Devon, the next phase of the trial will be as much about contracts and monitoring as about dams and wetlands. If the schemes are designed with clear baselines, realistic performance expectations and strong public oversight, they could provide a useful model for other catchments in the South West. If they are sold as a financial fix for complex ecological problems, the beavers may end up doing the work while the ledger tells a simpler story than the river can support.